 For professional partners
A Health Broker You Can Refer Clients To Without Worrying
When you send a client to someone, your name rides along. If they get upsold, ignored, or handed to a call center, that comes back to you. I built my practice so that never happens. CPAs, financial advisors, realtors, and HR teams send me their under-65 clients because I solve the coverage problem and stay out of the relationship they already have with you.
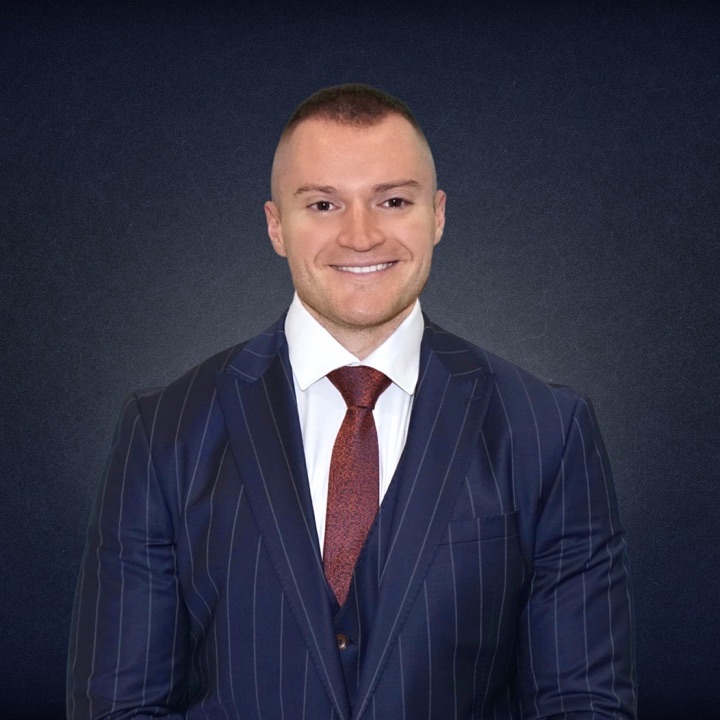
Ryan Michalek
Licensed Health & Life Insurance Agent · NPN 21043091 · Licensed in 31 states
I'm the independent broker your clients will actually talk to. I'm Tampa-based and five-star reviewed, and I'm the same person who answers the phone when they call back in July. More about me
Who already sends me clients
Professionals whose clients hit a health-coverage question they aren't licensed to answer, and who need somewhere safe to point them:
- CPAs & tax preparers: the client who just went self-employed, the S-corp owner asking about the premium deduction, the family that got a subsidy-repayment surprise at tax time.
- Financial advisors & planners: the client retiring before 65 who needs to bridge the gap to Medicare without wrecking the plan.
- Realtors & mortgage pros: the self-employed buyer who needs their own coverage sorted before closing.
- HR, payroll & PEO teams: the contractor or part-timer who falls outside the group plan, or the owner moving off a group entirely.
- Attorneys: the client coming out of a divorce, a layoff, or a new business formation who suddenly owns their own coverage.
- Insurance agents in other lines: the property & casualty, auto-and-home, commercial, or life-only agent whose client needs under-65 health coverage, a line you don’t write and don’t want to. Send it to a broker who won’t touch yours.
Why professionals send me their clients
No fee to your client
Brokers are paid by the carriers, never by the person. It costs your client nothing to talk with me or to enroll, so a referral never looks like you sent them to a bill.
No conflict with you
I'm a health broker. I solve the coverage question they came with and nothing else. I won't cross-sell your client or step on the relationship you've built.
Independent & licensed in 31 states
I'm not a call center and I'm not tied to one company, so I compare the real options and recommend what fits. Licensed in 31 states (NPN 21043091), based in Tampa.
Year-round, not just at enrollment
When a billing question or a confusing letter comes up mid-year, your client calls me, not a 1-800 number and not you.
Plain English, honest trade-offs
I explain what a plan does and doesn't do, in language a normal person follows. I skip the hype and the scare tactics, and I never call a plan “comprehensive” when it isn’t.
A reputation you can check
Five-star reviews on Google from real clients, BBB accredited, NABIP member. You can verify my license before you send a single person my way.
The clients I help most
I specialize in the under-65 people nobody’s HR department is looking out for, the ones who buy their own coverage. If a client of yours fits one of these, they're exactly who I help:
- Self-employed professionals & 1099 contractors
- LLC & S-corp owners sorting out the premium deduction
- Clients retiring before 65 who need to bridge to Medicare
- Earners over the subsidy cliff paying full freight on the marketplace
- Anyone between jobs or losing employer coverage
- Small-business owners covering themselves or a small team
- Families buying their own coverage
How a referral works
Send them my way
Forward this page, pass along my number (813) 833-7448, or make a quick email intro. No forms or portals to learn.
We talk, at no cost to them
A real conversation about their situation. I compare their options and explain the trade-offs in plain English.
They’re taken care of, and you look good
I get them covered and stay their broker year-round. With their okay, I’ll let you know it’s handled, so you can close the loop.
Copy a ready-to-send intro
Short on time? Copy this and paste it into an email or text to your client. It’s ready to go.
Hi, for your health insurance question, I’d talk to Ryan Michalek at Michalek Health Solutions. He’s an independent, licensed broker (not a call center), there’s no fee to you, and he’s good about explaining the options in plain English. You can reach him at (813) 833-7448 or book a time at michalekhealthsolutions.com. Tell him I sent you.
The moment to call me, profession by profession
Most coverage trouble I see could have been avoided by one phone call a few weeks earlier. You're usually the first professional to see the trigger coming, so here's what each of those moments looks like from my side, with the federal rule behind it. Rules checked November 8, 2026.
| If you are a | The moment you'll notice | Why the timing matters for coverage |
|---|---|---|
| CPA or tax preparer | A Form 8962 that comes back with a balance due, or a new Schedule C filer | Tax year 2026 is the first year with no cap on paying back excess advance premium tax credits, so a bad income estimate now costs more. I help the client pick a coverage path that fits a realistic number; the number itself is yours. See premium tax credit repayment. |
| Financial advisor or planner | A pre-65 client planning a Roth conversion, a business sale or a large gain | For 2027 coverage the subsidy stops at 400% of the poverty line, about $86,560 for a couple. A one-time taxable event can push a household over it for that year. Whether to time the event is your call; what it does to their coverage options is mine. See the subsidy cliff guide. |
| Realtor or loan officer | A self-employed buyer moving to a new county | A permanent move to a new ZIP code or county with different plans generally opens a 60-day window, but usually only if they had qualifying coverage for at least one day in the 60 days before the move. |
| HR, payroll or PEO team | An owner replacing a group plan with an ICHRA (now also called a CHOICE arrangement) or a QSEHRA | Being offered one is a qualifying event, with a window that opens 60 days before and runs 60 days after. For 2027, employer coverage meets the IRS affordability test, which blocks a subsidy, if the employee's own share is no more than 10.22% of household income. See small business coverage. |
| Family or employment attorney | A divorce, a separation agreement or a severance | Divorce by itself doesn't open an enrollment window; losing coverage because of it does. A spouse coming off a former partner's job plan can usually keep COBRA for up to 36 months, a severed employee for up to 18. See losing employer coverage. |
Sources: IRS Instructions for Form 8962 and the 2025 budget law's repeal of the repayment cap for tax years after 2025; IRS Rev. Proc. 2026-26 (10.22% for 2027); 2026 HHS poverty guidelines, Federal Register, January 15, 2026; HealthCare.gov, special enrollment periods; 29 U.S.C. 1162 (COBRA periods). General information for professionals, not tax or legal advice.
One client wrote in a Google review that when their finances changed partway through, I brought in a partner who set up the plan that fit, and I still followed up afterward to make sure all was well. That's the part I'd want you to know before you send anyone: the person you introduce to me doesn't get dropped once the first plan is in place.
I work alongside your advice
You know your client’s whole picture, from the tax situation to the retirement plan and the business, and I stay in my lane, which is health coverage. When a plan choice touches something you handle (how a premium is deducted, how income affects a subsidy, how a coverage decision fits the bigger plan), I’ll flag it and point your client back to you, because that’s your call to make, not mine. The goal is simple: your client gets the right coverage, and you stay the trusted advisor at the center of it.
It runs both ways
A good referral relationship goes both ways. My clients are self-employed people, families, and business owners, and they regularly need the exact professionals who send clients to me: a sharp CPA at tax time, an advisor for the retirement plan, an attorney for a divorce or a new entity, a loan officer when they buy a home. When one of mine needs help in your field, I’m glad to point them to a professional I trust. No fees change hands in either direction, since it’s two people looking out for the folks they send each other.
In their words
“Excellent customer service! … We also referred him to our neighbors and other business owners. 10/10!”
— Mishi C.
“Super knowledgeable and made the process quick and easy … I will be sending all my friends and family his way.”
— Jordan W.
“Ryan and his team found me the best health insurance for my needs and my budget, and were so honest and reliable … I would recommend them 100 times over.”
— Libby B.
Common questions from referral partners
Do my clients pay you anything?
No. Brokers are paid by the insurance carriers, not by the person. There's never a fee to your client to talk with me or to enroll in a plan.
Will you try to sell my client other products?
No. I'm a health insurance broker. I solve the coverage question your client came with and stay in that lane, so I won't cross-sell them or reach into the relationship you already have.
What kinds of clients should I send?
Under-65 people who buy their own coverage: the self-employed and 1099 contractors, LLC and S-corp owners, clients retiring before 65, anyone between jobs or losing employer coverage, families, and small-business owners.
How do referrals actually work?
Forward this page, share my number, or make a quick email introduction. We have a free conversation, and with your client’s permission I let you know it’s handled so you can close the loop.
Do you give tax or financial advice?
No, and I'm careful about that line. When a coverage decision touches tax or financial planning, I point your client back to you. Nothing I provide is legal, tax, or financial advice.
When is the best time to introduce a client to a health insurance broker?
Before the decision, not after it. The best introductions come before a client gives notice at a job, before a move closes, before a large income event like a business sale, and well ahead of the open enrollment deadline. Once coverage has lapsed or a window has closed, there are fewer options left to compare.
Will you share my client's health details with me?
No. What a client tells me about their health stays between us. With their permission, I'll let you know the coverage question is handled so you can close the loop, and if something touches your work, like an income estimate or a premium deduction, I'll point them back to you to discuss it directly.
Let’s set up a simple referral relationship.
There’s no paperwork, just a quick conversation so you know exactly who you’re sending people to. What day works for a 15-minute call? Have a client who needs coverage right now? Send them straight to the free cost estimator as an easy first step.
— Ryan Michalek, Licensed Health & Life Insurance Agent | NPN 21043091 | Tampa, FL