 No agenda · No rush
A Free Second Opinion on Your Health Coverage
Most people got one quote years ago and never looked again, and a lot of what matters only comes up once you talk it through. Bring me what you’ve got (or what you’re weighing) and I’ll help you understand your benefits and your rates. Whether you want coverage that actually fits, the richest coverage money can buy or just to make sense of what you already have, I’ll help you get there, even if it isn’t with me.
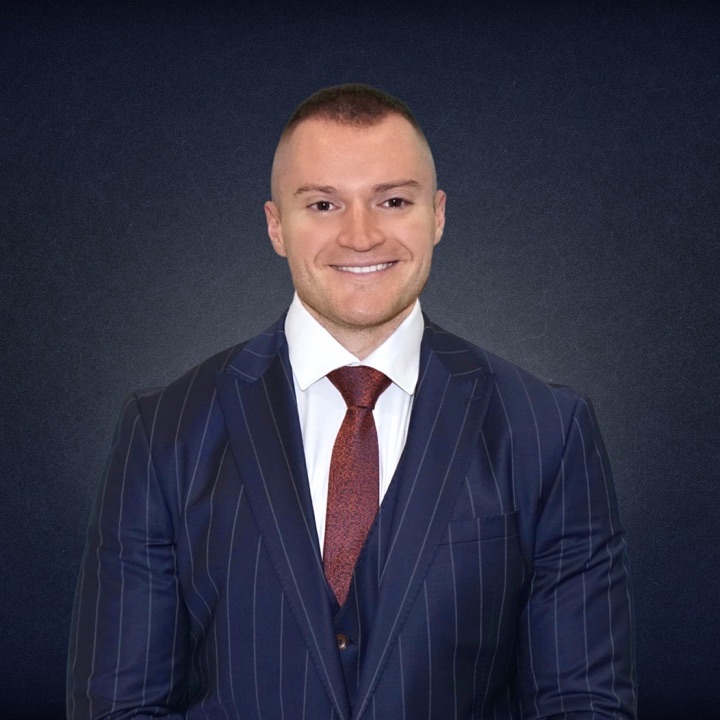
Ryan Michalek
Licensed Health & Life Insurance Agent · NPN 21043091 · Licensed in 31 states
I’m the independent Tampa broker you’ll actually talk to, the same person who picks up when you call back in July with a question, with no call center or script in between. More about me
Most People Never Look Again
Most people pick a health plan once, under a deadline, and never look at it again. Premiums creep up, plans quietly change what they cover, and life changes with a new job, a new baby, a business or a move. Unless someone actually walks through it with you, it’s hard to know whether you’re in the right plan or whether there’s a gap you haven’t noticed yet. A fifteen-minute call often turns up something that’s hard to spot on your own. Sometimes it turns up a better fit or catches a hole, and sometimes it just confirms that what you have is solid, which is worth knowing too.
Whatever You’re Looking For, I’ll Help You Get There
Watching every dollar?
I’ll show you what fits your budget, even if it isn’t a plan I’d earn a dime on. If the smartest move for your budget is somewhere else, I’ll tell you where to look.
Want the most coverage money can buy?
I’ll point you there too, and walk you through what that extra money actually buys you, so you’re paying up on purpose, not by accident.
Just want to understand it?
That’s my favorite conversation. Bring your questions, and you don't have to buy or switch a thing. We’ll just make sense of your benefits and your rates together.
I’ll tell you to keep it
If what you have is already a good fit, I’ll say so plainly and send you on your way. I won’t make up a reason to switch, and you won’t pay me a thing either way, since the carriers pay me, never you.
A Real Second Opinion I Gave
A healthy realtor in his fifties down in Miami came to me sure he was overpaying, since he never really uses his coverage and just wanted the least expensive plan that still capped his risk if something major ever happened. I went through his plan with him in detail, and the honest answer was that the only way to cut his rate was a short-term, limited-benefit plan that wouldn’t cover the exact “what if” scenarios he cared about most. So I told him straight: stick with what you have. It’s a medically underwritten plan with a real max out-of-pocket, and that protection is worth more than a lower premium that leaves you exposed. He thanked me for the time and for being straight with him, and that’s the whole job, even when the honest answer earns me nothing.
What I Actually Check When You Ask for a Second Opinion
"Is my health plan any good?" is the question people bring. It's really six smaller questions, and I go through them in this order, because the first one can make the other five moot. Rules and figures below checked November 8, 2026.
- Is it actually major medical? Some plans sold as health insurance are short-term or limited-benefit plans that cap what they pay or skip whole categories of care. The plan's Summary of Benefits and Coverage, the standard form every major medical plan has to provide, usually settles it in a minute. See what counts as major medical.
- Will it still be the same plan in January? If you have a marketplace plan and do nothing during open enrollment, HealthCare.gov says you may be re-enrolled automatically, and if your insurer stops offering plans for next year, it can move you to a plan with a different company. KFF counted 11 insurer exits for 2027 as of late October, so a quiet renewal is worth a look this year. See if your insurer is leaving.
- Are your doctors in it next year? Networks are set plan year by plan year. I check the specific doctors, the hospital you'd want and your prescriptions against next year's lists, not last year's card.
- What's the real worst case? The premium is the number everyone looks at. The out-of-pocket maximum is the one that matters in a bad year. For 2027, an ACA-compliant plan can't set the in-network maximum above $12,000 for one person or $24,000 for a family, and I look at where yours actually sits and what doesn't count toward it.
- Are you in the right metal level? If you pay full price, silver isn't automatically the middle-of-the-road choice. In my October 31, 2026 price checks, the lowest-priced gold plan came in under the benchmark silver premium for a 60-year-old in 17 of the 30 cities where both were offered. That isn't true everywhere, which is why I check yours. The full table is on what private health insurance costs.
- Does your income estimate still match your life? On a marketplace plan, the subsidy rides on the income you estimated. A new business, a raise, a spouse's job change or a drop in income can all move it, and from tax year 2026 any excess credit is paid back in full at tax time. I flag the mismatch; your tax preparer handles the number. See premium tax credit repayment.
Sometimes the answer goes the other way from what people expect. A couple of open enrollments ago, one family wrote in a Google review that they came to me ready to look elsewhere. After a short conversation, I told them the plans they were on were a good match and that they didn't need to move. What helped more was that their income had changed enough that help with the premium was now available to them on that same coverage. So they didn't switch anything and still had a better year, and that's the kind of second opinion I like giving.
What to send me first
- Your plan's Summary of Benefits and Coverage, or the plan name from your card or member portal
- Your renewal letter if you have one, since it shows next year's premium and any plan change
- The doctors, hospital and prescriptions you can't do without
- For a marketplace plan, the income you estimated on your application
Sources: HealthCare.gov, keep or change your plan (automatic re-enrollment); KFF, October 30, 2026 (11 insurer exits for 2027); CMS 2027 plan-year parameters guidance, January 29, 2026 ($12,000 / $24,000 out-of-pocket limit); IRS Instructions for Form 8962 and the repeal of the repayment cap for tax years after 2025; MHS 2027 marketplace price checks, October 31, 2026.
How a Second Opinion Works
Tell me what you’ve got
Your current plan, roughly what you pay, and what’s nagging at you, or just what you’re trying to figure out. A quick call, a text, or an email; whatever’s easiest for you.
We look at it together
I walk through your benefits and your rates in plain English, next to the real options out there. I skip the jargon and the scare tactics, and you don't have to change a single thing.
You get a straight answer
Keep what you have, tweak it, or here’s something that fits better, and if the right move is somewhere I can’t help, I’ll connect you with someone who can, and it’s always your call.
A Second Opinion Helps Most If You’re…
I work with under-65 people who buy their own coverage, the folks no HR department is looking out for. If you’re in one of these spots, a quick look is especially worth it:
- Self-employed or 1099 and buying your own plan
- An LLC or S-corp owner wondering if you’re set up right
- Retiring before 65 and bridging the gap to Medicare
- Over the subsidy cliff and paying full freight on the marketplace
- Staring at a premium that just jumped and wondering why
- Between jobs, on COBRA, or losing employer coverage
- Covering a family and not sure the plan still fits
In their words
“Excellent customer service! … We also referred him to our neighbors and other business owners. 10/10!”
— Mishi C.
“Super knowledgeable and made the process quick and easy … I will be sending all my friends and family his way.”
— Jordan W.
“Ryan and his team found me the best health insurance for my needs and my budget, and were so honest and reliable … I would recommend them 100 times over.”
— Libby B.
Common Questions
Does a second opinion cost anything?
No. It’s free, and there’s never a fee to talk with me or to enroll in a plan. The carriers pay me, not you.
Will you pressure me to switch?
No. If what you have is already a good fit, I’ll tell you to keep it. I only suggest a change when it helps you, and I won’t make up a reason to switch.
What if my plan is already good?
Then I’ll say so plainly, and you’ll walk away knowing it’s solid, which is a perfectly good outcome.
What do you need from me?
Just the basics of your current plan (or whatever you’re weighing), roughly what you pay, and whatever’s on your mind. A quick call, a text, or an email, whatever’s easiest.
Is this just a sales call in disguise?
No. I’ll point you to the option that fits your budget, the richest coverage, or nothing at all, whatever actually fits you, even if it isn’t a plan I offer.
Can you give a second opinion on a marketplace plan?
Yes. I'll look at a marketplace plan the same way I look at any other: whether it's the same plan next year, whether your doctors are in it, what the worst-case year costs and whether your income estimate still fits. If keeping it is the right call, I'll tell you. If a change on the marketplace makes sense, a licensed partner I trust handles that enrollment, and I stay your contact for questions.
Can you look at a plan before I buy it?
Yes, and that's often the most useful time. Send me the Summary of Benefits and Coverage or the plan details you're weighing, along with your doctors and prescriptions, and I'll tell you what it does well, where the gaps are and how it compares with the other options you have.
Let’s make sense of your coverage together.
There's no obligation, just a straight answer about your benefits and your rates. What day works for a 15-minute call? Want to poke around first? Try the free cost estimator as an easy place to start.
— Ryan Michalek, Licensed Health & Life Insurance Agent | NPN 21043091 | Tampa, FL